Meet Our 2027 FICO Decision Awards Judges
Top executives, media and analysts will evaluate how FICO customers are using AI and decisioning technology to drive measurable business outcomes

FICO has announced its panel of independent judges for the 2027 FICO® Decision Awards, which honor businesses achieving outstanding results using analytics and decision management technology to grow their business, manage risk and reduce costs.
“Our customers are adapting fast, using data, analytics, and technology to create better outcomes, and some of what they're building is remarkable,” said Nikhil Behl, president, Software at FICO. “The FICO Decision Awards, now in their 15th year, celebrate that progress, and I'm grateful to our eight independent judges for the expertise they bring.”
Winners will be announced in February 2027. For more information, visit www.fico.com/decisionawards
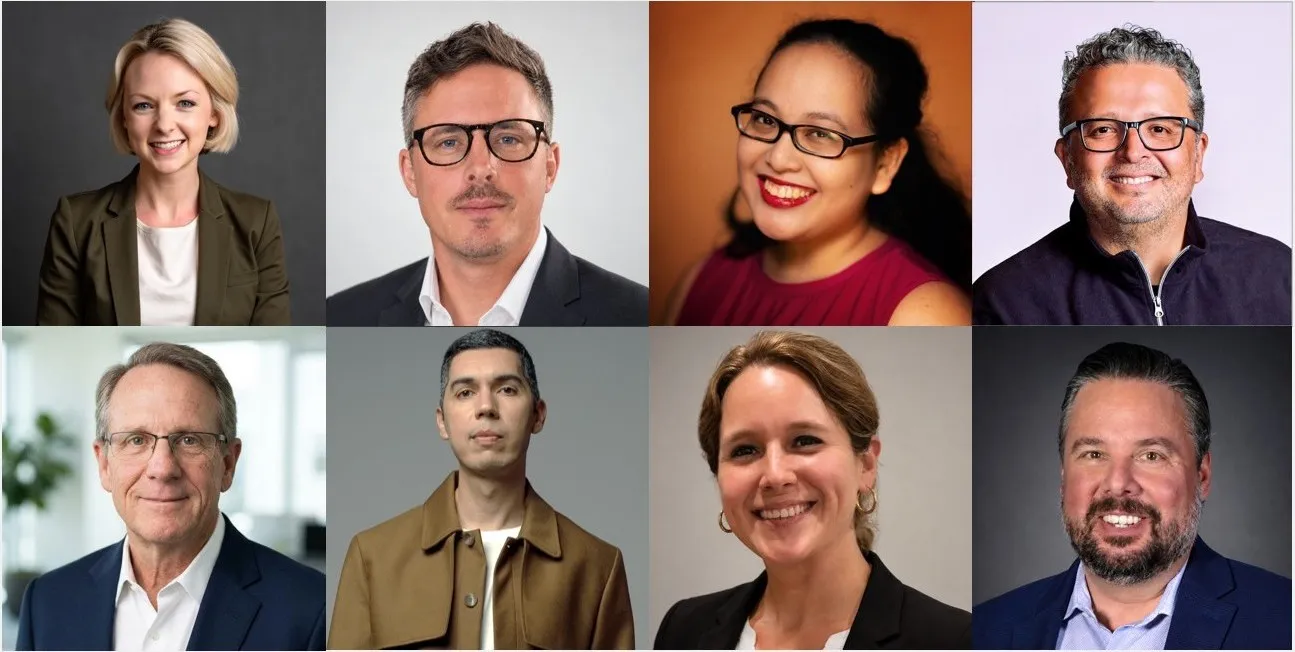
(2nd Row): Jim Mortensen, Vitor Cavalcanti, Melisa Osores, Rob Strechay
This year our judges, in alphabetical order, are:
- Vitor Cavalcanti, founder and CEO, Coletivo.tech
A journalist with more than 20 years of experience in content and communications, Vitor Cavalcanti leads Coletivo.tech, a Brazilian content and strategy platform focused on technology, business and society. He previously held senior leadership roles at IT Forum and as executive director of Movimento Brasil Digital, where initiatives he led, including free digital-skills courses and national research on 5G's economic potential and Brazil's digital competitiveness, reached millions of Brazilians. Vitor is a PhD candidate in business administration at Fundação Getulio Vargas and a member of the Harvard Business Review Advisory Council.
- Emilia David, associate editor, Enterprise AI and Technology, ISMG
Emilia David has spent close to 20 years in journalism, much of it reporting on how financial institutions manage risk and adopt new technology. She covered banking operational risk and capital markets for four years at WatersTechnology, then moved into venture capital reporting at Venture Capital Journal and Insider before joining The Verge and then VentureBeat as senior AI reporter, where she wrote the weekly AI orchestration newsletter. She joined ISMG in mid-2026, continuing to cover enterprise AI across the application layer, infrastructure, policy and productivity, with a focus on how banks and enterprises separate real AI value from hype.
- Amy Lamb, head of development & industry relations, National Foundation for Credit Counseling (Previous Winner)
With nearly two decades of experience across the nonprofit and technology sectors, Amy Lamb specializes in strategic partnerships, philanthropy, program strategy and consumer financial wellness. She now heads development and industry relations at NFCC, the United States' largest and longest-serving nonprofit financial counseling organization, working with industry partners and NFCC Member Agencies to fund and implement solutions that improve consumers' financial health. Her portfolio includes Life Beyond Debt, an initiative pairing fintech tools with trusted human financial guidance to give consumers in debt a personalized path toward financial stability.
- Adam Mills, AI editor, Newsweek
Adam Mills leads AI Impact, a weekly Newsweek newsletter focused on how artificial intelligence is changing the way businesses operate, compete and create value. His reporting covers enterprise AI adoption, governance, financial crime compliance and the changing economics of technology, with recent work examining AI agents, software and services business models, workforce adoption and decision-making inside large organizations. With more than 15 years of experience as an editor, consultant and writer, Adam brings a practical lens to where AI is delivering measurable business value, where companies are struggling to scale it and what those lessons mean for business leaders. He is a graduate of San Diego State University and is based in Long Beach, California.
- Jim Mortensen, strategic advisor, Fraud & AML, Datos Insights
Jim Mortensen is a strategic advisor in Datos Insights’ Fraud & AML practice, covering identity, fraud and data security. With more than 30 years of financial services experience, he has worked extensively in fraud prevention, identity verification, credit underwriting, analytics and risk management for leading financial institutions around the world. Prior to Datos Insights, Jim held senior roles at Equifax, Early Warning Services and American Express. At Early Warning Services, he led the Identity Solutions product line and its risk advisory committee of fraud and security executives from major banks. Earlier at American Express, he helped develop underwriting and fraud strategies supporting the company’s international card businesses across Asia, Europe and Latin America.
- Melisa Osores, managing editor for Latin America, Informa TechTarget
With nearly 30 years of experience writing and editing specialist technology media in Mexico and Peru, Melisa Osores now leads Latin American coverage for Informa TechTarget, overseeing ComputerWeekly en Español's reporting on IT strategy, cybersecurity and enterprise AI adoption across the region. Earlier in her career, she led corporate communications for organizations in IT, tourism, security, health and services, and spent nine years as deputy editor of PCWorld Perú and Computerworld Perú, contributing regularly to outlets including InformationWeek México and b:Secure. She holds a degree in information sciences from Universidad de Piura.
- Rob Strechay, lead analyst, VentureBeat Intelligence
Rob Strechay advises technology providers and enterprise leaders on AI, cloud-native infrastructure, data, observability and cyber resilience, most recently as VentureBeat's first Lead Analyst and a founding analyst of VentureBeat Intelligence. He founded Smuget Consulting after nearly three decades spanning startups and Fortune 500 companies, including executive and analyst roles at Amazon Web Services, HPE, NetApp, Zerto, TechTarget's Enterprise Strategy Group, and most recently as managing director and principal analyst at theCUBE Research and SiliconANGLE. His commentary on AI and enterprise infrastructure has appeared in Forbes, The Wall Street Journal, CRN and CIO, alongside his own coverage for VentureBeat.
- Jaime Vargas, senior director, credit risk strategy, T-Mobile (Previous Winner)
At T-Mobile, Jaime Vargas was part of the team that cut deployment cycles by more than 50% while processing over a million monthly credit applications with zero downtime, work that won a 2026 FICO Decision Award. He now leads credit risk strategy there, bringing deep FICO Platform expertise to the judging panel from twelve years at FICO in analytic consulting and practice leadership across the Americas and Asia Pacific, plus senior credit risk roles at Santander Bank. Jaime holds an MBA from Indiana University of Pennsylvania and a BSc in industrial engineering from Universidad de Los Andes.
The 2027 Awards will be presented across a refreshed line-up of eight categories: AI & Analytics; Digital Transformation; Customer Lifecycle; Decision Management Innovation; Fraud & Scam Defense; Financial Inclusion & Empowerment; Pioneer Award; Industry Vanguard Award.
Winners will receive recognition at FICO® World, which will be held April 19–22, 2027 at the Marriott Marquis San Diego Marina hotel in San Diego, California. Winning implementations will be featured in conference activities, and two representatives of each winning company will receive complimentary conference passes.
Last year's winning firms represented multiple industries and countries worldwide, all with outstanding results: Erste Group & Inditex (AI, Machine Learning & Optimization); Banco Santa Cruz (Cloud Deployment); T-Mobile & Banco Atlántida (Customer Onboarding & Management); Absa (Debt Management); Bradesco (Decision Management Innovation); AFRY (ESG Champion); Grab Finance & NFCC (Financial Inclusion); Santander Brazil & Barclays (Fraud Management); BNZ (Pioneer Award); and TSYS, Compeer Financial & SentiLink (FICO Industry Vanguard Award).
Popular Posts

Average U.S. FICO® Score at 716, Indicating Improvement in Consumer Credit Behaviors Despite Pandemic
The FICO Score is a broad-based, independent standard measure of credit risk
Read more
The GSE Data Is Public. Here's What It Shows About Credit Score Modernization.
Independent Milliman analysis of GSE historical data confirms what anyone can now verify directly: FICO® Score 10T is the most predictive score.
Read more
FICO® Score High Achievers: Is Age the Only Factor?
<p>FICO’s latest research on <a href="http://www.fico.com/en/blogs/risk-compliance/us-credit-quality-rising-the-beat-goes-on/" target="_blank">national FICO® Score distribution</a> shows that US credit quality continues to trend upwards, with an increasing number of consumers scoring in the highest scores ranges. Given that, we decided it was time to refresh our study on “<a href="http://www.fico.com/en/blogs/risk-compliance/infographic-what-does-a-high-credit-scorer-look-like/" target="_blank">FICO® Score high achievers</a>,” where we examine the credit behavioural profiles of consumers with higher credit scores.</p> <p>As expected, our latest study showed that older people generally have higher scores, as has been the case in our <a href="http://www.fico.com/en/blogs/risk-compliance/age-before-beauty-credit-worthiness-before-youth/" target="_blank">past research</a>. This is largely because they have trade lines that have been open longer, which leads to higher scores (assuming the trade lines are in good standing and all other things equal). The most credit savvy among you will remember that length of credit history accounts for roughly 15% of the overall <a href="http://www.myfico.com/CreditEducation/WhatsInYourScore.aspx" target="_blank">FICO® Score calculation</a>.</p> <p>But for younger consumers, it isn’t too helpful to say, “just wait until you are 50 years old, and that will fix things!” Thus, I decided to dive deeper with our analysis, including looking at the credit behavioural characteristics of younger consumers with high FICO® Scores.</p> <p>In this analysis, I looked at credit characteristics for the two highest score bands, 750-799 and 800-850, which have about 16% and 23% of the population, respectively. I further broke this down by looking at the characteristics of the youngest 15% in each group, which occurs at age 29 for the 750-799 group and 43 for the 800-850. We used FICO<strong>®</strong> Score 9 for our analysis, and examined typical variables of the categories that go into the make-up of the score.</p> <p><a href="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png"><img class="alignnone size-full wp-image-29367" src="http://www.fico.com/en/blogs/wp-content/uploads/2016/10/FICO-Score-High-Achiever-table.png" alt="fico-score-high-achiever-table" width="715" height="747" /></a></p> <p>Since there’s a lot to dissect in this chart, I’ll highlight a few findings that struck me: <ul> <li><strong>Credit history.</strong> Higher scores are undoubtedly associated with a longer time on file. What’s striking is the higher average time on file for the 800+ group, both overall and for revolving accounts (the most common trade line). Clearly, it helps to start credit use early in life – but that’s not the sole determining factor for high scoring. The younger cohorts in both the 800+ and 750-799 groups have time on file medians significantly less than their older counterparts.</li> <li><strong>New credit.</strong> High credit scorers do, in fact, pursue new credit. We see little variation in months since last trade line opening and last inquiry among all groups observed.</li> <li><strong>Pay on time.</strong> As you might expect, the further in the past the delinquency, the higher the score – and that’s <u>if</u> a delinquency ever happened. 95% of the 800+ people and 72% of the 750-799 group have never been delinquent, which is a striking contrast to the 57% for the total population. The percentages for the younger groups are even higher, especially so for the 750-799ers. Collection items are also scarce for these high scorers. While 23% of the national population have collection items greater than $99, the figures are only 0.5% for the 800+ group and 3% for the 750-799 group. It is clear that, in conjunction with starting a credit file early, paying on time is a key trait of the FICO® Score high achiever.</li> <li><strong>Balance and utilization.</strong> Finally, we look at how credit is being used, focusing on revolving product use. (Since most people only have one mortgage or one auto loan, variation in instalment product figures is minimal and driven by payment history, which is near perfect for high scorers, as we’ve seen.) FICO® Score high achievers tend to have more open revolving accounts. While the % active trades and utilization are generally lower, by no means do high scorers avoid the use of credit products. What drives the difference here is the amount of <u>available</u> revolving credit utilized. The 800+ group is roughly 1/4 of the national median, both in total and on their highest utilized card; they also have lower balances and more cards<em>. </em>The 750-799 group is more active and higher utilized, but still only at 2/3 of the national figures. The young 750-799 group compensate with lower revolving balances and, as a result, lower utilization, which is in line with what we see for the 800+ group.</li> <li><strong>Benchmarks.</strong> I’d like to point out that while this study provides good benchmarks of the typical credit traits of the FICO® Score high achiever, individual credit profiles will vary widely. And keep in mind that when we sort groups of consumers as a whole by different behaviours, some results may look superficially odd. For example, the 800+ band has a longer median average open account time (128 months) than average revolving months on file (140 months).</li> </ul> So, what do we conclude? A huge takeaway is that high scorers don’t have too much in the way of serious delinquencies and negative public record data.</p> <p>In most respects, the young 800+ people are like their peer group. They really only differ markedly in their shorter credit history and higher non-mortgage balance, both of which are a function of life stage. Our results show that you don’t have to be a credit product hermit; these high scorers have more credit cards. The takeaway is to start credit activity early and maintain well-managed and moderate usage.</p> <p>In many ways, the young 750-799 people are more interesting because their age profile is much younger. Their credit characteristics differ more from their peer group, particularly in terms of length of credit history. They compensate by having almost pristine credit records and lower balances.</p> <p>Ultimately, 39% of US consumers are FICO® Score high achievers, which they accomplish by following common-sense credit practices. It ain’t rocket science!</p>
Read moreTake the next step
Connect with FICO for answers to all your product and solution questions. Interested in becoming a business partner? Contact us to learn more. We look forward to hearing from you.